Is It Cheaper to Renovate or Move in 2027?
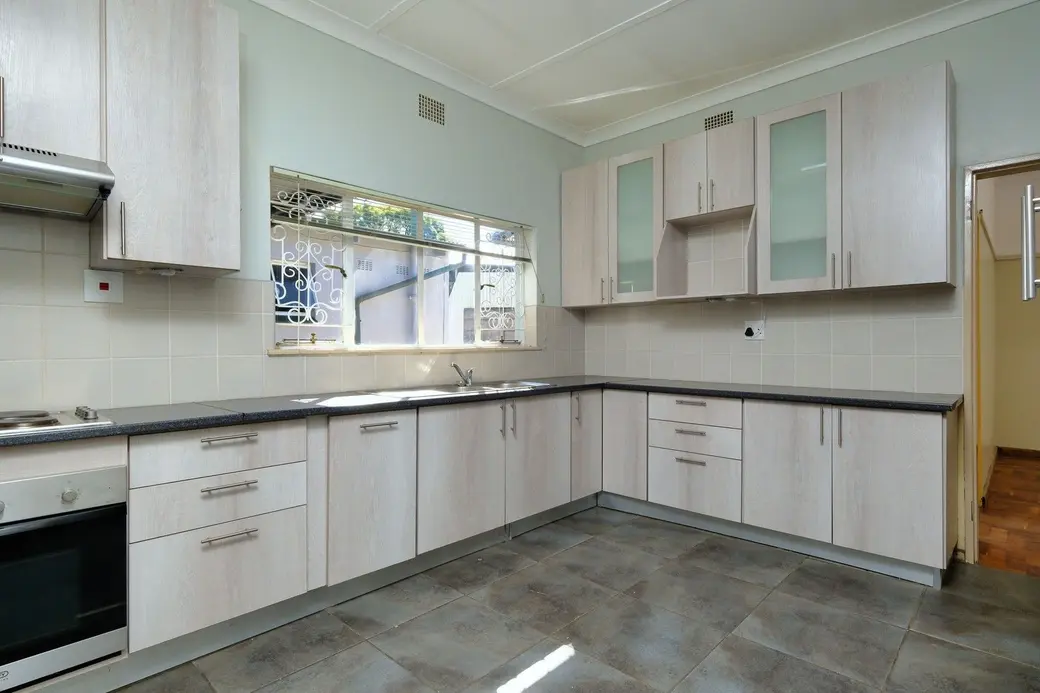
You're staring at the same kitchen. The same stairs. The same layout that worked ten years ago.
So is it cheaper to renovate… or sell and move?
This is the fourth post in my series The Real Cost of Staying Put in South Denver. I've already covered why Colorado home insurance is so high, Colorado's 2027 property reassessment, and HELOC vs cash-out vs moving.
The Short Answer
- Renovate usually wins when the bones are good and you just need the house to work better — especially if you're keeping a low mortgage rate.
- Move usually wins when the layout, lot or location is the real problem. No amount of granite fixes that.
- Don't compare a remodel quote to zero. Compare it to selling costs, buying costs and a new loan at today's rates.
What Remodels Actually Cost (and What They Return)
The 2025 Cost vs. Value Report (Zonda / Remodeling) is the closest thing we have to national "what do buyers pay you back for" data. A few midrange national averages:
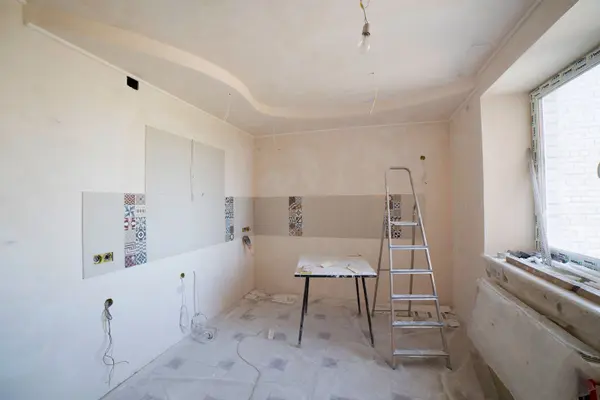
- Minor kitchen remodel: about $28,500 to do, roughly 113% of cost recouped at resale.
- Midrange bath remodel: about $26,100, roughly 80% recouped.
- Major midrange kitchen remodel: about $82,800, roughly 51% recouped.
- Primary suite addition: about $170,500, roughly 32% recouped.
- Basement remodel: about $52,000, roughly 71% recouped.
Notice the pattern? Smaller, targeted updates tend to return more of your money. Big, personal additions often don't.
HomeAdvisor's cost guides put a typical kitchen remodel around $27,000 (often $15,000–$42,000) and a typical bath around $12,000 (often $7,000–$18,000). Angi puts a multi-room remodel around $52,000 on average. Your Centennial or Highlands Ranch bid will land where your finishes, labor and permits land.
Want the South Denver version of which projects actually help? Here's what home improvements actually add value.
What Moving Actually Costs
Moving isn't free just because you're "done" with the house.
On the sell side: Broker compensation is fully negotiable and not set by law. After the NAR practice changes, offers of buyer-broker compensation can't be advertised in the MLS (REcolorado followed that in 2024). You may still negotiate listing fees and any contribution toward a buyer's broker — or not. On a $650,000 sale, even a negotiated few percent is real money. Sellers in Colorado also commonly cover owner's title insurance and their share of closing fees.
On the buy side: Bankrate puts typical mortgage closing costs around 2% to 5% of the loan amount (lender fees, title, appraisal, prepaid taxes and insurance). In Denver Metro right now, many sellers are sweetening deals too — DMAR reported that 65% of October 2026 sales included a seller concession, averaging about $12,600.
The rate reset: Freddie Mac's 30-year average was 7.18% as of Nov. 5, 2026. If your current rate is 3% or 4%, moving means that new payment is on today's rates — on whatever you finance.
And yes, there's temporary housing, movers and the chaos tax. I don't put a fake number on those unless you've got real quotes.
A Simple Side-by-Side (My Math, Rounded, Not a Quote)
Assume a South Denver detached home around the DMAR year-to-date detached median of $650,000. You've got a $300,000 mortgage at 3%.
- Stay and renovate: midrange minor kitchen + midrange bath from Cost vs. Value ≈ $55,000 all-in project spend. Keep the $300,000 loan. Principal and interest stays about $1,265/month.
- Sell and buy something similar: Illustrative negotiated selling costs of 5% on $650,000 = $32,500 (not a standard rate — yours will differ). Buy another $650,000 home with 20% down and finance $520,000 at 7.18%: about $3,523/month principal and interest.
That's roughly $2,250 more per month to end up in a similar-priced house — before you count buyer closing costs or moving. The $55,000 remodel suddenly looks cheap next to that payment jump.
If you're upsizing or downsizing, the math changes. Run it. I walk through the downsizing version in Does Downsizing Actually Save Money?
When Renovate Wins
- You love the location (Centennial schools, Greenwood Village commute, Cherry Hills Village feel, Lone Tree access, Littleton charm, Highlands Ranch amenities).
- The house is the right size — it just needs a kitchen, bath or basement that works.
- You're keeping a low first-mortgage rate. (If you need to borrow for the project, compare a HELOC first — that's HELOC, cash-out or move.)
- The project is cosmetic or midrange, not a $170,000 addition you'll never get back.
When Move Wins
- Stairs, bedrooms, yard or lot size don't match your life — and can't without a gut job.
- You're paying to fix a house you already want to leave.
- A different South Denver pocket solves more than new cabinets would.
- Your current rate is already near today's rates, so the "lock-in" advantage is gone.
If you're stuck between the two, start with Should I Stay, Renovate or Move?
Leaning toward selling in the spring? Start with my winter home prep checklist before a spring sale.
A Few Questions to Ask Yourself
- Would this remodel make me want to stay five more years?
- Am I fixing the house, or fixing my life with the house?
- What does a net sheet look like if I sell today?
- What would my payment be on the next house at today's rates?
- Is this a Cost vs. Value project — or an "I want it" project? Both are fine. Just don't confuse them.
Want Real Numbers for Your House?
I'll put together a free home value analysis so you can compare a remodel budget against what you'd net if you sold — no pressure, no yard sign.
Thinking about listing? Grab my free Seller's Guide. Call or text 720-935-7537.
Frequently Asked Questions
Is it cheaper to renovate or move in 2027?
It depends. Renovating is often cheaper if you keep a low mortgage rate and the house mostly fits. Moving can win when the layout or location is wrong, but you pay selling costs, buying costs and a new loan at today's rates — around 7.18% for a 30-year fixed as of early November 2026.
How much does a kitchen or bath remodel cost?
The 2025 Cost vs. Value Report puts a midrange minor kitchen remodel around $28,500 nationally and a midrange bath remodel around $26,100. HomeAdvisor's averages are about $27,000 for kitchens and about $12,000 for baths, with wide ranges based on finishes and scope.
Do home remodels pay for themselves at resale?
Usually only in part. Cost vs. Value shows a midrange minor kitchen recouping about 113% nationally, a midrange bath about 80%, a major midrange kitchen about 51%, and a primary suite addition about 32%. Live-in value matters too — not just resale.
What closing costs should Colorado sellers and buyers expect?
Broker fees are fully negotiable and not set by law. Buyers often budget about 2% to 5% of the loan amount for mortgage closing costs. Sellers typically cover negotiated listing compensation, often owner's title insurance in Colorado, and any concessions. In October 2026, DMAR said 65% of Denver Metro sales included a seller concession averaging about $12,600.
When does moving beat renovating?
When the house itself is the problem — wrong floor plan, wrong lot, wrong location — or when a remodel would cost nearly as much as the payment shock of a new mortgage. If the bones and location are right, a targeted remodel plus keeping your rate usually wins on cost.
The Real Cost of Staying Put in South Denver
- Why Is My Colorado Home Insurance So High (and What Can I Do)?
- Colorado's 2027 Property Reassessment: What South Denver Homeowners Should Know
- HELOC, Cash-Out or Move? Using Your Equity at 7% Rates
- Is It Cheaper to Renovate or Move in 2027? (you're reading it)
- Winter Home Prep That Protects Your Value Before a Spring Sale
Let's Run Your Numbers
If you're in Centennial, Greenwood Village, Cherry Hills Village, Lone Tree, Littleton, Highlands Ranch or anywhere in the South Denver Metro, I'm happy to compare a remodel budget against a sell-and-buy plan with real local numbers.
Stay. Renovate. Move. No pressure. Just a plan.
Devin @ The W Real Estate Group
General information only, not tax, legal, lending, contracting or financial advice. Remodel costs and recoup rates are national averages from the sources below and vary by home and market. Broker compensation is negotiable. The payment and cost examples are my own rounded math, not quotes — talk to a lender, contractor and tax professional about your situation.
Sources
- Zonda / Remodeling, 2025 Cost vs. Value Report (national averages); overview at Zonda
- HomeAdvisor, Kitchen Remodel Cost Guide and Bathroom Remodel Cost Guide (updated 2026)
- Angi, Multiple-Room Remodel Cost Guide (updated Oct. 30, 2026)
- Freddie Mac, Mortgage Rates Decline for Third Consecutive Week to 7.18% (Nov. 5, 2026)
- Bankrate, Closing Costs: What They Are and How Much You'll Pay (updated Nov. 2, 2026)
- REcolorado, Navigating Compensation Changes in Real Estate; NAR, Dispelling 7 Myths About NAR's Proposed Settlement
- DMAR, Real Estate Market Trends Report | October 2026 (Nov. 4, 2026)
Categories
Recent Posts
GET MORE INFORMATION