Why Is My Colorado Home Insurance So High (and What Can I Do)?
Your renewal shows up.
You open it.
And you read the number twice.
If that's happened to you, you're not alone. I hear it from homeowners all over South Denver.
"Our mortgage is fine. It's the insurance that's killing us."
So let's talk about why Colorado home insurance costs what it does, and what you can actually do about it.
This is the first post in a new series: The Real Cost of Staying Put in South Denver. Because staying in your home has costs too, and they're worth knowing before you decide anything.
The Short Answer
Why is home insurance so high in Colorado?
Hail.
Not wildfire. Not your neighborhood. Mostly hail.
Add higher rebuilding costs and a few rough years for insurers, and premiums have climbed fast.
The good news: you have more control than you think. Your roof, your deductible, your discounts and how often you shop all matter.
What Colorado Homeowners Are Paying
Here's what the numbers show.
Insurify estimated the average Colorado home insurance premium at $4,137 a year in mid-2026, up 3.5% in just the first half of the year.
Insurify also reports the average Colorado premium has risen 55% since 2023.
That's not a small bump. On a lot of South Denver homes, insurance is now a real piece of the monthly payment.
Why Hail Is the Big Driver
The Colorado Division of Insurance asked 20 insurers, covering about 80% of the market, to break down what drives premiums.
What they found:
- Hail accounts for 26% to 54% of the premium, depending on the county.
- Along the Front Range, it's roughly half of what homeowners pay.
- Wildfire is a much smaller piece in most metro counties. In Denver, it's about 1% of the premium.
In the Division's Denver example, about $1,547 of a $3,040 average premium was tied to hail.
Insurers spread hail risk across the whole state. So even if your street hasn't been hit in years, you're still paying for it.
What You Can Do About It
1. Shop your policy every year or two
The Division of Insurance's first tip is simple: shop around and compare insurers.
Compare coverage, not just price. A cheap quote with a thin policy isn't a deal.
2. Know your wind and hail deductible
Many Colorado policies have a separate wind/hail deductible that's a percentage of your coverage, often 1%, 2% or 5%.
On a home insured for $600,000, a 2% deductible is $12,000 out of pocket before insurance pays.
Find it on your declarations page. A higher deductible can lower your premium, but only choose one you could actually pay after a storm.
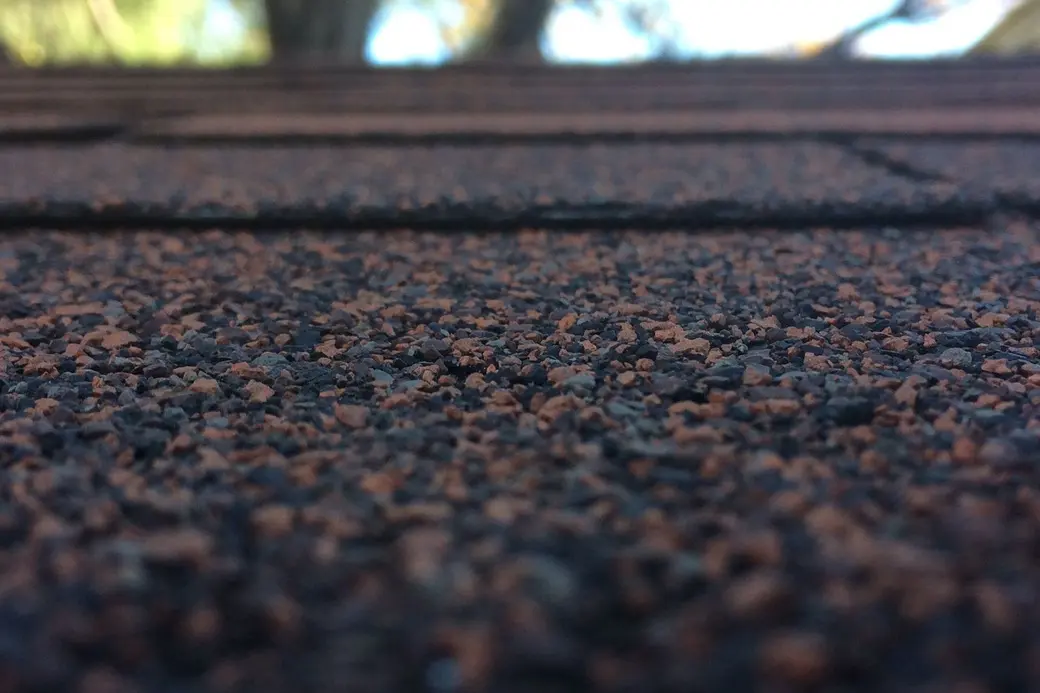
3. Ask about a hail-resistant roof
This is the biggest lever.
The Division found hail mitigation, like a fortified or impact-resistant roof, could save homeowners an average of $82 to $387 a year, depending on the county.
If your roof is near the end of its life anyway, ask your agent what discount an impact-resistant roof would earn before you pick shingles.
Colorado also created the Strengthen Colorado Homes Enterprise in 2026 (Senate Bill 26-155) to offer grants for stronger roofs against hail and wind. Watch the Division's page for details as the program rolls out.
4. Ask for every discount
Bundling home and auto, home hardening and updated systems can all earn discounts.
Keep records of your roof, furnace, electrical and plumbing updates. Insurers like proof.
5. Check your reports
Insurers can use consumer reports, like claims history, when pricing your policy. The Division notes you can request your reports and check them for errors.
6. Make sure your coverage still fits
Ask your agent what it would cost to rebuild your home today. Too little coverage is a risk. Paying for coverage you don't need is wasted money.
Does This Change Whether You Should Stay or Move?
Sometimes.
Insurance alone usually isn't a reason to move. But it adds up with everything else: taxes, repairs, utilities and the roof that's coming due.
That's the whole point of this series. Staying put isn't free. Moving isn't either. You want to compare the real numbers side by side.
If you're weighing it, start with Should I Stay, Renovate or Move?
Thinking about a smaller place to cut costs? Here's whether downsizing actually saves money.
And if you're considering upgrades first, see what home improvements actually add value. A new roof is one of the few that can pay you back twice: at resale and on your insurance bill.
Free: Fall 2026 South Denver Seller's Guide
Weighing whether to stay, renovate or move? My free Fall 2026 Seller's Guide walks through prep, pricing, timing and what to expect in today's market.
Want to see your real numbers? Ask me for a free home value and equity analysis. No pressure, no sign in the yard. Call or text 720-935-7537.
Frequently Asked Questions
Why is home insurance so expensive in Colorado?
Hail is the biggest driver. The Colorado Division of Insurance found hail accounts for 26% to 54% of homeowners premiums depending on the county, and about half along the Front Range. Rising rebuilding costs and insurer losses have also pushed premiums up.
How much is home insurance in Colorado?
Insurify estimated the average Colorado premium at about $4,137 a year in mid-2026. Your price depends on your home, roof, coverage amount, deductible and claims history.
What is a wind and hail deductible?
Many Colorado policies have a separate deductible for wind and hail claims, set as a percentage of your dwelling coverage, often 1%, 2% or 5%. On a home insured for $600,000, a 2% deductible means paying the first $12,000 of a hail claim.
Does a hail-resistant roof lower insurance in Colorado?
Often, yes. The Colorado Division of Insurance found hail mitigation such as fortified roofs could save homeowners an average of $82 to $387 a year depending on the county. Ask your insurer what discount applies before you replace your roof.
Should I raise my deductible to lower my premium?
It can lower your premium, but choose a deductible you could comfortably pay after a storm. With a percentage hail deductible, that number can be much larger than you expect.
The Real Cost of Staying Put in South Denver
- Why Is My Colorado Home Insurance So High (and What Can I Do)? (you're reading it)
- Colorado's 2027 Property Reassessment: What South Denver Homeowners Should Know (coming soon)
- HELOC, Cash-Out or Move? Using Your Equity at 7% Rates (coming soon)
- Is It Cheaper to Renovate or Move in 2027? (coming soon)
Let's Look at Your Real Cost of Staying
If you're in Centennial, Greenwood Village, Cherry Hills Village, Lone Tree, Littleton, Highlands Ranch or anywhere in the South Denver Metro, I'm happy to sit down and look at your numbers with you.
Stay.
Renovate.
Or move.
No pressure.
Just a plan.
Stay. Renovate. Move.
Devin @ The W Real Estate Group
This article is for general information only and isn't insurance, legal, tax or financial advice. I'm a real estate broker, not an insurance agent; talk with a licensed insurance professional about your policy. Figures are from the sources below as of October 2026 and will change. The $600,000 deductible example is for illustration only.
Sources
- Colorado Division of Insurance, Hail is the Number One Cost Driver of Insurance in Colorado (one-pager)
- Colorado Department of Regulatory Agencies, Governor Polis and Division of Insurance: We Must Find Innovative Solutions to Save Colorado Homeowners Money on Insurance Costs
- Colorado Division of Insurance, Toolkit for Homeowners and HOAs on Insurance
- Colorado Division of Insurance, Consumer Advisory: Tips to Prepare for Hailstorm
- Colorado Division of Insurance, Strengthen Colorado Homes Enterprise and Colorado General Assembly, SB26-155
- Insurify, Home Insurance Rates Continued Rising in the First Half of 2026 and Home Insurance Price Projections
Categories
Recent Posts
GET MORE INFORMATION